Equipment breakdown insurance, sometimes called boiler and machinery coverage, pays to repair or replace equipment that fails because of a sudden mechanical or electrical breakdown. For a food business, that means the refrigeration, cooking equipment, HVAC, electrical panels and specialty machines that the whole operation depends on. It is usually added to the property section of a commercial package for food businesses.
How insurers write it varies: spoilage limits, expediting expenses and income extensions are not the same from one policy to the next. Because we work with several insurers that want food and hospitality business, our brokers can compare those terms for you and explain the differences in plain language.
What it covers that property insurance does not
Property insurance is designed for damage that comes from outside the machine: fire, smoke, theft, a burst pipe, a storm. Most property policies specifically exclude mechanical breakdown, electrical injury and boiler explosion. That leaves a big hole in a kitchen, where equipment runs hard for long hours.
| What happened | Property insurance | Equipment breakdown |
|---|---|---|
| Fire in the kitchen damages the range | Usually covered | Not needed |
| Cooler compressor burns out on its own | Usually excluded | Covered |
| Power surge destroys the oven’s control board | Often excluded | Covered |
| Electrical arcing damages the main panel | Often excluded | Covered |
| Thief steals the espresso grinder | Usually covered | Not needed |
| Fryer worn out after ten years | Not covered | Not covered |
Equipment breakdown generally requires a sudden and accidental cause. It is not a maintenance contract or a warranty, and it does not pay for parts that simply wear out.
Real examples from kitchens and hospitality
Walk-in cooler compressor
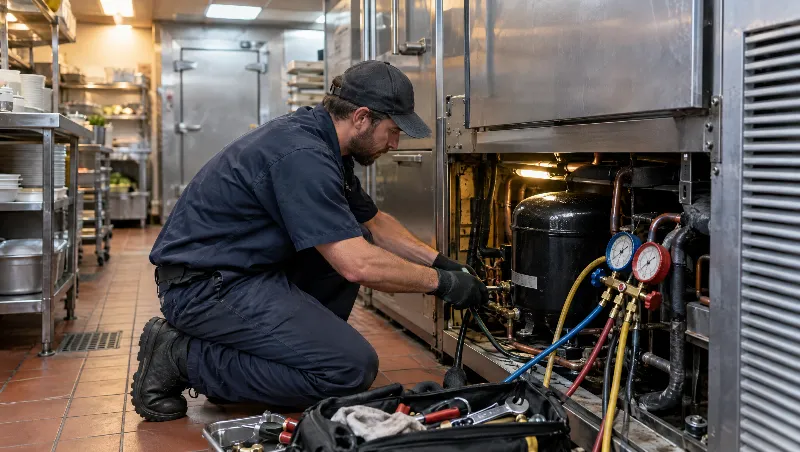
The compressor in a walk-in fails on a humid July night. By morning the box is warm. Equipment breakdown pays for the replacement compressor and the refrigeration technician. Spoilage coverage, if you added it, pays for the meat, dairy and prepped food that had to be thrown out.
Combi oven control board
Combi ovens are expensive and depend on electronic control boards. A board failure can take an oven out for days while a part is shipped. Equipment breakdown pays for the board and labour, and expediting expense coverage can pay to fly the part in overnight.
Espresso machine
For a café, the espresso machine is the business. An electrical fault in the boiler element or a failed pump means no lattes until it is fixed. Our page on coverage for coffee shops looks at how cafés set this up, including leased machines.
HVAC, heating and kitchen ventilation
When a rooftop unit or the make-up air system fails, the kitchen can become too hot to work in or fail a ventilation requirement. In an Ontario winter, a failed boiler or furnace can close a dining room just as quickly. Equipment breakdown covers the failed unit. For hotels, it also covers boilers, chillers and the systems that keep guest rooms comfortable.
Electrical arcing
Arcing in an electrical panel or switchgear can damage the panel itself and every piece of equipment fed from it. It is one of the more expensive breakdown events and is often excluded from standard property cover.
Example: A power surge during a summer thunderstorm hits a busy diner in London, Ontario. The surge fries the control boards on two fryers, the dish machine and the walk-in’s condenser. Property insurance declines the claim because there was no fire or physical damage from outside. Equipment breakdown pays to repair all four units, spoilage pays for the lost stock, and expediting expenses cover overtime for the electrician so the diner reopens two days sooner.
Spoilage add-on
Spoilage coverage pays for perishable stock that is lost when refrigeration fails, whether because of a breakdown or a power outage. It is commonly offered as an add-on to equipment breakdown, with its own limit. If you carry a lot of refrigerated or frozen inventory, such as a steakhouse, a bakery with wholesale orders or a brewery with cold storage, set the limit to reflect what you actually hold at your busiest time.
Some policies also cover spoilage caused by an outage that starts off your premises. We check whether each option we bring you does.
Expediting expenses
Expediting expenses cover the extra cost of getting repairs done faster: overnight shipping for parts, overtime for technicians, and temporary repairs. For a business that loses revenue every day it is closed, these costs are often far smaller than the income they save. They also work alongside income protection during a closure, because the shorter the shutdown, the smaller the income loss.
Other things the policy can include
- Data restoration after a breakdown wipes a point-of-sale server or reservation system.
- Code upgrades when the replacement has to meet a newer standard.
- Green upgrades to more energy-efficient equipment after a loss, in some policies.
- Hazardous substance cleanup, such as refrigerant release.
What equipment breakdown does not cover
- Wear and tear, rust, corrosion and gradual deterioration.
- Equipment you do not maintain, especially with no service records.
- Vehicles, including food trucks on the road. Those need commercial auto.
- Liability to customers. A guest hurt by a faulty machine is a liability matter for the general liability policy.
- Damage from external events that the property policy should cover.
Keep service records for refrigeration, hoods and gas equipment. They help at underwriting and are often the first thing an adjuster asks for after a claim.
Which business do you run?
The equipment that can stop your business depends on what you do. Find your type of operation below for coverage advice written for it.
- Coverage for sit-down restaurants with table service, with full lines, walk-ins and dish machines.
- Insurance for quick-service and takeout counters, where fryers and holding cabinets run all day.
- Coverage built for retail and wholesale bakeries, with deck ovens, proofers and spiral mixers.
- Insurance for coffee shops and cafés, where the espresso machine and grinders carry the day.
- Coverage for mobile kitchens and food trucks, with generators and compact refrigeration.
- Insurance for caterers and event kitchens, with combi ovens and mobile hot boxes.
- Coverage for bars, pubs and taverns, with draft systems, ice machines and glass washers.
- Insurance for craft breweries and taprooms, with brewhouses, glycol chillers and canning lines.
- Coverage for wineries and tasting rooms, with presses, pumps and temperature-controlled tanks.
- Insurance for hotels, motels and inns, with boilers, chillers, elevators and laundry equipment.
- Coverage for bed and breakfasts and guest houses, where a furnace or hot water failure affects every guest.
Getting a quote for equipment breakdown
Fill in the short form on this page or call us at (416) 346-6886. One of our brokers helps you list the equipment your business depends on and set sensible spoilage limits. We take your application to insurers that suit your operation, walk you through the options and set up the policy you choose. After that, we stay with you for certificates, changes, renewals and claims.
Common questions
Isn't equipment already covered by my property insurance?
Property insurance covers equipment damaged by external events like fire, theft or water. It usually excludes mechanical and electrical breakdown, where a machine fails from the inside. Equipment breakdown covers that gap.
Does equipment breakdown cover wear and tear?
No. It covers sudden and accidental breakdown, such as a motor burning out or a power surge frying a board. Gradual wear, corrosion and a lack of maintenance are generally excluded, which is why service records matter.
Does it cover leased equipment?
Often, yes, if your lease makes you responsible for the equipment. Many espresso machines, dish machines and ice makers are leased, so list them when you talk to our brokers and we will check how the lease terms fit the policy.
Will it pay for the food I lose when the cooler dies?
Only if your policy includes spoilage coverage, which is commonly offered as an add-on to equipment breakdown. We will include it and help you set a limit if you hold significant refrigerated stock.
Does equipment breakdown cover my income while I'm closed for repairs?
It can, if the policy includes a business income extension or your business interruption coverage is extended to equipment breakdown. We confirm the waiting period, which can be different from the one on your property policy.